
Every parent in Delhi wants to give their child the best possible start in life. You picture good schools, a comfortable home, and a future free of money worries. But school fees, college costs, and even wedding expenses keep rising every single year, often faster than most families expect. Simply parking your savings in a regular fixed deposit account rarely grows fast enough to keep up with these rising costs. This is exactly why so many families are now choosing a child plan fixed deposit in Delhi to build a strong financial cushion for their child’s future. It is a simple, low-risk way to turn today’s savings into tomorrow’s opportunities, without exposing your hard-earned money to market ups and downs.
The Problem With Traditional Fixed Deposits
Most traditional financial institutions provide very low interest rates on fixed deposit accounts, often ranging from 4% to 5% per annum. But if the inflation rate is at 6-7%, the money potentially loses its purchasing power every year. If the money stays invested in traditional FD accounts for a long time while the inflation rate keeps rising, it can lose half of its value. You will see a higher balance in your bank, but its actual purchasing power will be very low, as compared to what it used to be.
Start Early, Let Time Do the Heavy Lifting
The price of a college degree in India keeps climbing every year. A course that costs around ten lakh rupees today could easily cost thirty lakh rupees or more by the time your child is ready to enroll. Weddings follow the same pattern, with costs rising steadily as the years go by. These are large expenses that are nearly impossible to arrange at the last minute without a plan.
The good news is that time works in your favor when you start early. When you invest while your child is still young, your money gets many years to grow through the power of compounding. Even a modest amount set aside today can turn into a large sum later, taking real pressure off your family when it matters most. Parents who begin early often find they can meet big goals without taking on loans or debt.
How Do Cooperative Societies Offer Better Growth?
Cooperative societies work differently from regular financial institutions. A cooperative thrift & credit society like Samridh Bharat focuses solely on making profits for all of its members. All the profits of the society are equally distributed among all the members. In contrast, a conventional financial institution focuses on making more money for its shareholders rather than the customers who invest their hard-earned money in its platforms.
Samridh Bharat is one of the most trustworthy cooperative societies in Delhi for diverse investment tenures for all families. We provide a 12.82% interest rate per annum on a child plan fixed deposit in Delhi with our Swarnim Bhavishya Yojna: a long-term investment plan. Moreover, Samridh Bharat operates under the Delhi Cooperative Societies Act 2003, which ensures the safety, transparency, and accountability of our operations.
Swarnim Bhavishya Yojna by Samridh Bharat
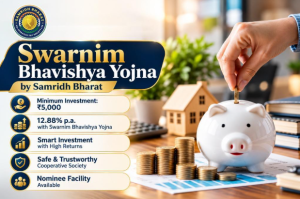
Swarnim Bhavishya Yojna stands out as a dedicated child savings investment plan for many families across India. A lump sum amount of money is invested for 19 years, and after completing the tenure, you get a 10x return on the investment.
Here’s what that growth looks like:
| Amount Invested | Tenure | Amount You Receive |
| ₹5,000 (minimum) | 19 years | ₹50,000 |
| ₹1,00,000 | 19 years | ₹10,00,000 |
| ₹5,00,000 | 19 years | ₹50,00,000 |
You can start with as little as five thousand rupees, which makes it easy for almost any family to begin, regardless of income level. There is no upper limit on how much you can invest, and you can open more than one account if you wish to save separately for different goals.
Swarnim Bhavishya Yojna vs Other Child-Saving FDs
Parents often weigh a few different paths before settling on one plan. Here’s how this kind of scheme stacks up against two common alternatives.
Girl-child Savings Schemes from Government: This investment limits you to one account per girl child, with a maximum of two accounts per family. Your yearly deposit is capped, interest usually tops out around eight percent, and the account only matures after twenty-one years. A cooperative child savings plan places no such limits on you, welcomes both boys and girls equally, and matures in just nineteen years at a much higher interest rate.
Several other conventional investment plans are often marketed as strong long-term options, but they carry real risks that many parents often overlook. Returns move up and down, as they’re bounded by market volatility, management fees quietly eat into your gains, and past performance is never a promise of future results. A fixed deposit plan, by contrast, gives you a guaranteed, fixed return with none of that uncertainty, which matters greatly when the goal is your child’s education. You know exactly how much you will receive and when, so you can plan school admissions or wedding dates without guessing whether the money will actually be there.
Perks That Go Beyond the Interest Rate
Along with strong returns, these plans come with practical features that make everyday life easier for your family.
- No TDS – your interest earnings stay free from tax deduction.
- Emergency Loans – borrow up to ninety percent of your deposit value if urgent needs arise.
- Lower Minimum Deposit – begin your savings journey with just five thousand rupees.
- Flexible Investment Tenure – pick a duration that matches your child’s school or college timeline.
- Prematurity Withdrawal – withdraw your funds early, with applicable interest, if life takes an unexpected turn.
- Nominee Facility – keep your family protected with a named nominee on the account.
Simple Steps to Get Started
Opening this kind of account is easier than most parents expect. Here’s what the process usually looks like:
- Decide on your investment amount, starting from as little as five thousand rupees.
- Choose a tenure that fits your child’s milestones, such as college or marriage.
- Submit a government ID & address proof to complete membership.
- Add a nominee to ensure the safety of the invested funds.
- Track your deposit’s growth and plan withdrawals around your child’s financial needs.
Final Words
Your child’s future depends on the choices you make right now. Waiting too long or settling for a low-interest savings account can cause a significant burden, while starting early lets your money do the heavy lifting on its own. An ideal child plan fixed deposit in Delhi gives your family an assured, stress-free way to fund your child’s education, wedding, or other big milestones.
Frequently Asked Questions
Q1. What is the minimum investment amount for a child’s fixed deposit plan in India?
At Samridh Bharat, the minimum amount for a child FD is 5,000 in the Swarnim Bhavishya Yojna investment plan.
Q2. What are the documents required to open a child’s fixed deposit account in Delhi?
The parent’s Aadhaar, PAN, and affidavit are required. You also need the child’s Birth Certificate and photos. Also, the parent must first be a registered society member, by declaring that they’re not a member of any other thrift & credit cooperative society.
Q3. Can I withdraw the investment before the tenure ends?
Yes, prematurity withdrawal is available at the applicable interest rate.
Q4. Is the loan against fixed deposit available?
Yes. Individuals can take a loan up to 90% of their invested amount in emergency situations.